
Should You Focus on Debt Collection or Cash Flow? (The Answer Will Surprise You)
Ever stared at your aging receivables report and felt that knot in your stomach tighten? You’re not alone. For small business owners across Australia, the question burns hotter than ever: “Should I drop everything to chase these overdue invoices, or invest that time into fixing my cash flow systems instead?”
It’s the business equivalent of “chicken or egg” – and getting it wrong could cost you everything.
But before we talk about which problem you should solve first, let’s talk about why these two issues deserve your immediate attention in the first place.

The Hidden Costs of Poor Cash Flow and Unpaid Invoices You Can’t Afford to Ignore
Cash flow problems are like termites in your business foundation – silent, destructive, and they multiply when ignored. When combined with mounting unpaid invoices, the damage compounds in ways that can sink an otherwise thriving business.
Most business owners understand the obvious impact, not being able to pay bills or make payroll. But the truly devastating effects actually run deeper:
Operational paralysis
When you’re constantly putting out cash fires, nothing moves forward. That expansion you planned? That new product line? All stuck on permanent hold while you scramble to cover this month’s bills.
Capital shortage
Every dollar in unpaid invoices is money not working for your business right now – cash that should be funding operations, inventory, marketing, or growth opportunities.
Missed business opportunities
That perfect inventory deal requiring quick payment? That rock-star hire who needs a competitive salary? Lost to competitors who had cash ready to strike when opportunity knocked.
Wasted time
The average business owner spends 15+ hours monthly chasing payments – valuable time you can’t spend on revenue-generating activities. That’s before counting legal expenses or collection agency fees.

Decision fatigue
The daily stress of money problems drains your energy and kills your creativity – the very skills that got your business off the ground in the first place.
Damaged business relationships
Suppliers who get paid late start demanding up-front payments. Employees who see cash fluctuations begin updating their resumes. And the awkward dance of payment follow-up with clients can permanently strain valuable relationships if not handled properly.
And as you know, word spreads fast in business circles.
The Domino Effect
Late payments trigger more late payments as your own obligations start slipping, creating a vicious cycle that’s increasingly difficult to break.

Where to Focus 100% of Your Time, Energy, and Money: A Strategic Framework
So what’s the answer to our chicken-and-egg dilemma? The truth is situational, but there’s a clear framework to guide your decision:
1. Survival Mode
If you’re facing any of these scenarios, debt recovery must be prioritised:
- Cash reserves below 30 days of operating expenses
- Payroll or critical vendor payments at risk
- Tax obligations are coming due without funds to cover them
- Multiple creditors threatening legal action
In these business emergencies, deploy the “oxygen mask principle” – secure your own cash position before attempting systemic improvements.
2. Stabilisation Phase
Once the immediate fire is out, balance your efforts:
- Spend most of your time (70%) setting up better cash flow systems
- Use the rest (30%) to collect your most valuable outstanding invoices
- Make simple policy changes (update trading and payment terms) that help with both goals at once
This balanced approach works because chasing some old debts isn’t worth your time, while preventing new problems gives you the biggest payoff.
3. Growth Phase
When your business is stable again, shift your focus to building strong systems:
- Create simple cash flow forecasts to spot problems before they happen
- Screen clients better before working with them
- Set clear payment terms and stick to them
- Set up automatic payment reminders that escalate when needed
- Look into financing options that keep your cash flow steady
Good systems mean fewer unpaid invoices in the future – solving both problems at once.

8 Practical Steps to Improve Your Cash Flow and Debt Recovery Simultaneously
While your focus may shift based on your situation, certain actions can benefit both sides of the equation. Here are a few business hacks on how you can improve both your cash flow and debt recovery at the same time.
1. Segment your receivables
Categorise by age, amount, and probability of collection. Focus first on the newest, largest amounts from reliable clients.
2. Perfect your collection communication
Replace generic “payment due” messages with specific, benefit-oriented reminders.
✅ To maintain your priority scheduling status, please process payment by Thursday.
❌ Your invoice is overdue” every time.
3. Offer strategic payment options
Partial payments, payment plans, or even small discounts for immediate payment can convert “won’t pay” into “will pay something now.”
4. Consider professional intervention
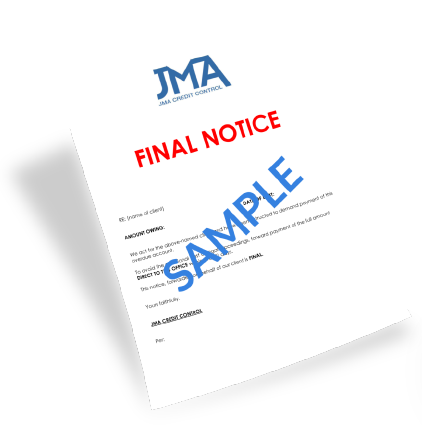
When invoices age beyond 90 days, the probability of collection drops dramatically. A professional debt recovery service like JMA Credit Control often becomes your most cost-effective option.
5. Implement deposit requirements
For new clients or large orders, a 30-50% upfront payment can protect you from devastating losses.
6. Tighten your invoicing cycle
Send invoices immediately upon delivery, not at the end of the month. Use electronic delivery with read receipts.
7. Establish clear payment terms
Vague terms lead to vague payment timelines. Spell out exactly when payment is due and what happens if deadlines pass.
8. Create a systematic follow-up protocol
Predetermined escalation paths remove emotion from collection efforts and ensure consistent action.
The businesses that thrive don’t view this as an either/or proposition. They recognise that targeted debt recovery creates breathing room while improved systems prevent future cash flow problems.

When to seek help from professional debt recovery experts
The debt recovery vs. cash flow management question doesn’t have a one-size-fits-all answer. Your specific situation dictates your starting point, but the destination remains the same: a business with strong cash flow systems and minimal payment problems.
For many businesses, the turning point comes when they recognise they can’t excel at both simultaneously. This is where we come in.
JMA Credit Control specialises in helping small businesses recover what they’re owed while providing guidance on preventing future payment problems. If debt recovery is something that you’re not great at or you simply don’t want to do, it might be better to delegate it to the experts.
Contact us today for a confidential assessment of your accounts receivable situation.